Hurricane Roof Insurance in Florida: Coverage Requirements, Claims, and Best Practices
Florida homeowners face unique challenges when it comes to roof insurance. The state's vulnerability to hurricanes has created a specialized insurance landscape with specific requirements, higher deductibles, and complex claim procedures. Understanding how hurricane roof insurance works in Florida helps homeowners prepare adequately and navigate claims successfully when storms strike.
Florida's Unique Insurance Landscape
Florida's insurance market differs significantly from other states due to hurricane exposure and regulatory responses.
Market Characteristics:
- Higher premiums than national averages
- Limited carrier availability in high-risk areas
- State-run Citizens Insurance as insurer of last resort
- Specialized hurricane deductible structures
- Strict building code requirements
Why Florida Is Different:
The state experiences: - More hurricane landfalls than any other state - Significant claim volumes after major storms - Insurer financial pressures and exits - Regulatory intervention to maintain market - Ongoing rate and coverage controversies
Understanding Hurricane Deductibles
Hurricane deductibles in Florida work differently than standard deductibles and often surprise homeowners when claims arise.
How Hurricane Deductibles Work:
Percentage-Based:: Most Florida policies use percentage deductibles: - Calculated as percentage of dwelling coverage - Typically 2%, 5%, or 10% - Triggered by named hurricanes
Deductible Calculation Example:
| Dwelling Coverage | 2% Deductible | 5% Deductible | 10% Deductible |
|---|---|---|---|
| $300,000 | $6,000 | $15,000 | $30,000 |
| $400,000 | $8,000 | $20,000 | $40,000 |
| $500,000 | $10,000 | $25,000 | $50,000 |
Trigger Conditions:
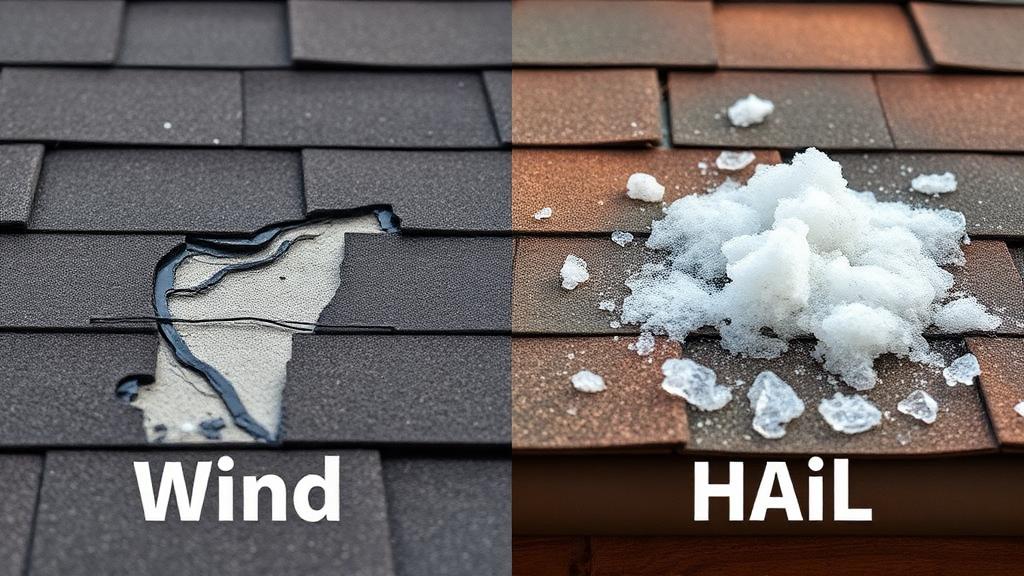
Hurricane deductibles apply when: - National Hurricane Center declares named storm - Storm is hurricane strength at landfall - Damage occurs during specified window - Wind is primary cause of damage
Planning for High Deductibles:
Prepare financially by: - Understanding your deductible amount - Maintaining emergency savings - Considering lower deductible options (higher premium) - Evaluating self-insurance for smaller storms
Florida Building Code Requirements
Florida's building codes directly impact both roof insurance and claims.
Florida Building Code Evolution:
After Hurricane Andrew (1992): - Significant code strengthening - Wind resistance requirements - Impact-resistant material standards - Installation method specifications
Current Code Highlights:
- Wind load requirements vary by region
- Roof-to-wall connection standards
- Shingle installation specifications
- Secondary water barrier requirements
How Codes Affect Insurance:
Coverage Benefits:: - Code-compliant roofs may qualify for discounts - Better coverage terms for modern construction - Improved claim outcomes for up-to-code repairs
Claim Considerations:: - Repairs must meet current code - Code upgrades may be covered - Non-compliance may affect claims
Wind Mitigation Credits
Florida law requires insurers to offer discounts for wind-resistant features. Understanding these credits can significantly reduce premiums.
What Wind Mitigation Inspections Cover:
Inspectors evaluate: - Roof covering type and condition - Roof deck attachment method - Roof-to-wall connections - Roof geometry (hip vs. gable) - Secondary water resistance - Opening protections (shutters, etc.)
Potential Savings:
Wind mitigation features can reduce premiums by: - 15-45% for roof covering upgrades - 5-15% for roof deck attachment - 10-30% for roof-to-wall connections - Significant cumulative savings possible
Getting Wind Mitigation Credits:
To qualify: 1. Schedule wind mitigation inspection 2. Inspector documents qualifying features 3. Submit report to insurance company 4. Premium adjusted at renewal
Filing Hurricane Damage Claims
Hurricane claims in Florida follow specific procedures with important deadlines and requirements.
Immediate Post-Storm Steps:
- Ensure Safety - Address immediate dangers first
- Document Damage - Photograph and video extensively
- Prevent Further Damage - Temporary repairs allowed
- File Claim Promptly - Contact insurer immediately
Documentation Requirements:
Comprehensive documentation includes: - Before-storm condition photos (if available) - Damage photographs from multiple angles - Video walkthroughs of damage - Weather reports confirming hurricane - Timeline of discovery and response
Florida-Specific Deadlines:
Be aware of critical timelines: - Claim filing: Typically within policy period - Supplemental claims: Within policy provisions - Statute of limitations for lawsuits
Working with Adjusters After Hurricanes
High claim volumes after hurricanes affect adjuster availability and inspection quality.
What to Expect:
After major hurricanes: - Significant adjuster deployment - Longer wait times for inspections - Possible use of less experienced adjusters - Remote or virtual inspections sometimes used
Maximizing Inspection Outcomes:
- Be present during inspection
- Prepare comprehensive documentation
- Have contractor estimates ready
- Point out all damage areas
- Ask questions about findings
Requesting Re-Inspection:
If initial inspection seems inadequate: - Document concerns in writing - Request different adjuster - Provide additional evidence - Consider public adjuster assistance
Common Hurricane Claim Issues
Florida hurricane claims frequently encounter specific challenges.
Assignment of Benefits (AOB) Concerns:
AOB arrangements: - Transfer claim rights to contractors - Have created significant litigation - May complicate your claim - Require careful consideration before signing
Lowball Settlement Offers:
If your settlement seems inadequate: - Request detailed explanation - Get independent contractor estimates - Submit formal dispute - Consider public adjuster or attorney
Claim Denials:
Common denial reasons: - Pre-existing damage allegations - Maintenance-related exclusions - Flood damage attribution (requires separate policy) - Policy limitations or exclusions
Citizens Property Insurance
Many Florida homeowners rely on Citizens, the state-run insurer of last resort.
Understanding Citizens:
Citizens provides coverage when: - Private market options unavailable - Private quotes exceed Citizens rates - Coverage needed in high-risk areas
Citizens Considerations:
- May have coverage limitations
- Assessment risk if Citizens faces losses
- Depopulation efforts move policyholders to private market
- Policy terms may differ from private insurers
Preparing for Hurricane Season
Proactive preparation improves both safety and insurance outcomes.
Pre-Season Checklist:
Insurance Review:: - Review policy coverage limits - Understand deductible amounts - Verify adequate replacement cost coverage - Consider flood insurance
Property Preparation:: - Get roof inspected - Address any maintenance issues - Install hurricane shutters or impact windows - Secure loose items
Documentation:: - Photograph home condition - Document valuable possessions - Store records safely (cloud backup) - Know your policy location
Financial Preparation:: - Understand deductible requirements - Maintain emergency fund - Know claim filing process - Have contractor contacts ready
Finding Insurance in Florida
Navigating Florida's challenging insurance market requires strategy.
Market Navigation Tips:
- Work with independent agents who access multiple carriers
- Consider Citizens if private options limited
- Compare coverage carefully, not just price
- Verify carrier financial stability
- Understand all policy provisions
Reducing Costs:
Lower premiums through: - Wind mitigation improvements - Higher deductible acceptance - Bundling policies - Maintaining claim-free history - Installing safety features
After the Claim
Post-claim actions protect your future coverage and investment.
Recovery Best Practices:
- Complete repairs using qualified contractors
- Ensure code compliance
- Document all work performed
- Maintain receipts and warranties
- Update wind mitigation report
Future Planning:
- Review insurance annually
- Maintain property documentation
- Keep emergency fund for deductibles
- Consider coverage improvements
Conclusion
Hurricane roof insurance in Florida requires understanding unique market conditions, high deductible structures, and specific claim procedures. By preparing before hurricane season, documenting thoroughly when damage occurs, and navigating claims effectively, Florida homeowners can protect their homes and recover from storm damage successfully.
Stay informed about Florida's evolving insurance landscape, maintain your property to code requirements, and work with professionals who understand the state's unique challenges.
Find Florida roofing contractors experienced with hurricane damage and insurance claims.