Insurance Coverage for Aging Roofs: Understanding Depreciation, Limits, and Options
As roofs age, insurance coverage becomes more complicated and often more expensive. Understanding how age affects your roof's insurance coverage helps you make informed decisions about maintaining protection, timing replacement, and navigating claims. This comprehensive guide explains everything homeowners need to know about insuring aging roofs.
How Roof Age Affects Insurance Coverage
Your roof's age significantly impacts multiple aspects of your insurance coverage.
Coverage Type Changes:
Replacement Cost Value (RCV):: - New roofs typically qualify for RCV - Pays full replacement cost without depreciation - May be limited or unavailable for older roofs - Better protection but higher premiums
Actual Cash Value (ACV):: - Pays replacement cost minus depreciation - Often required for older roofs - Significant out-of-pocket for claims - Lower premiums but less protection
Age Thresholds:
| Roof Age | Typical Coverage Changes |
|---|---|
| 0-10 years | Full RCV usually available |
| 10-15 years | May shift to ACV, higher rates |
| 15-20 years | Often ACV only, restrictions |
| 20+ years | Limited coverage, possible non-renewal |
Understanding Depreciation
Depreciation is the reduction in value due to age, wear, and remaining useful life.
How Depreciation Is Calculated:
Common methods include: - Straight-line depreciation (equal amount per year) - Remaining useful life percentage - Condition-based assessment
Depreciation Example:
For a 15-year-old roof with 25-year expected life: - Replacement cost: $20,000 - Age: 15 years - Depreciation rate: 60% (15/25) - Depreciation amount: $12,000 - Actual cash value: $8,000
Impact on Claims:
With ACV coverage: - Settlement offer: $8,000 - Minus deductible: -$1,500 - You receive: $6,500 - Out-of-pocket for replacement: $13,500
Coverage Limitations for Older Roofs
Insurance companies impose various restrictions on older roof coverage.
Common Restrictions:
Schedule Limitations:: Some policies include roof schedules specifying: - Coverage type based on age - Maximum settlement amounts - Specific exclusions - Deductible modifications
Coverage Exclusions:: Older roofs may face: - Cosmetic damage exclusions - Matching provisions removed - Partial coverage limitations - Higher specific deductibles
Policy Availability:
With aging roofs, you may encounter: - Fewer carriers willing to insure - Higher premium requirements - Required inspections before coverage - Non-renewal notices
Insurance Company Policies on Roof Age
Different insurers handle aging roofs differently, creating opportunities and challenges.
Typical Insurer Approaches:
Conservative Insurers:: - Strict age limitations - Mandatory inspections - Quick shift to ACV - Non-renewal for older roofs
Moderate Insurers:: - Flexible age thresholds - Condition-based decisions - Extended RCV availability - Reasonable rate adjustments
Specialized Markets:: - Accept older roofs - May have higher rates - Different terms and conditions - Limited availability
Shopping Strategy:
For aging roofs: - Work with independent agents - Compare multiple carriers - Evaluate coverage, not just price - Consider specialized markets - Review all policy terms carefully
Inspections for Older Roofs
Insurance companies often require inspections before covering or renewing policies on older roofs.
What Insurers Look For:
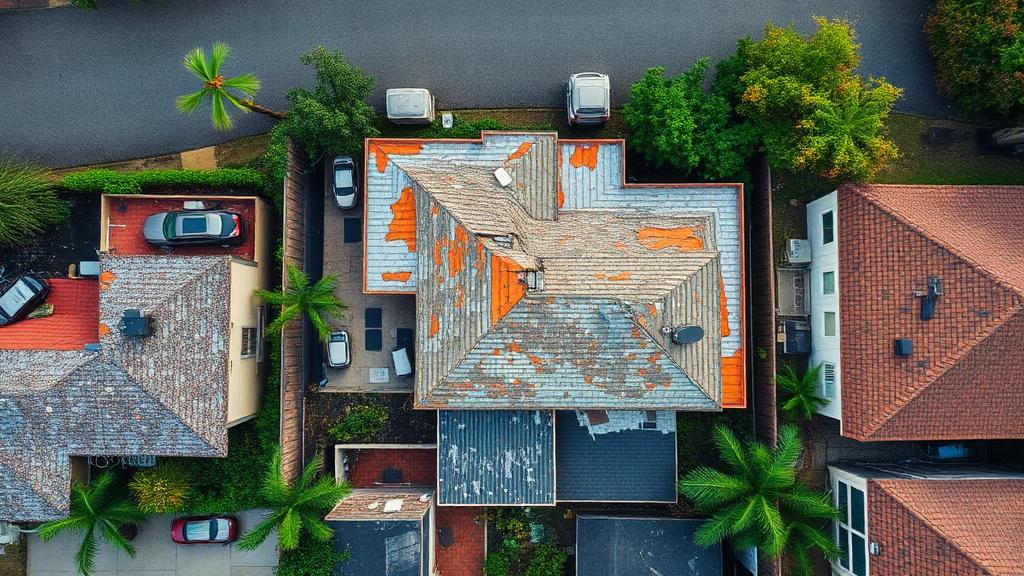
Condition Assessment:: - Overall wear and deterioration - Missing or damaged shingles - Flashing condition - Signs of previous repairs - Estimated remaining life
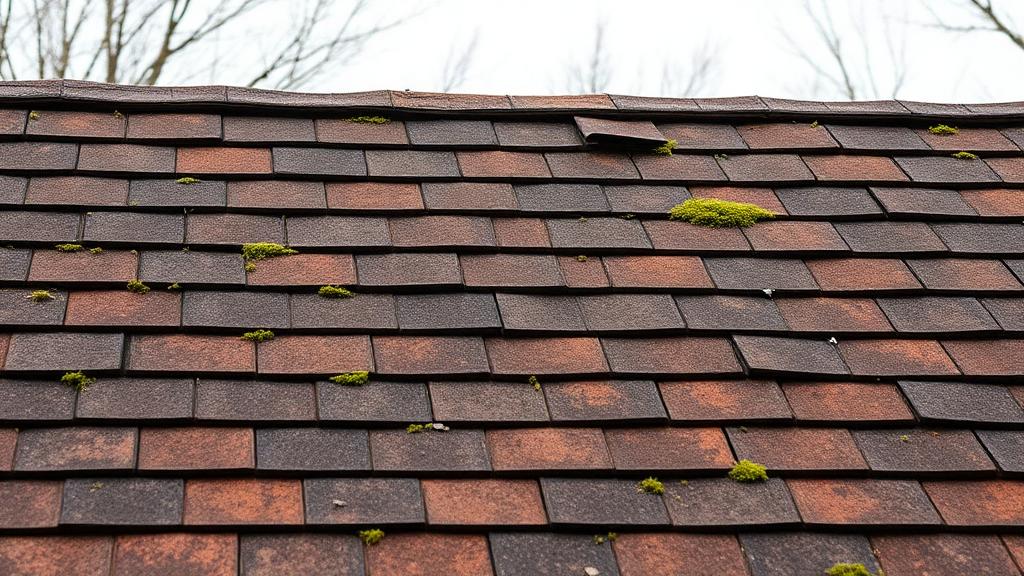
Maintenance Indicators:: - Clean gutters and drainage - No moss or debris accumulation - Proper ventilation function - Evidence of regular care
Potential Problems:: - Active leaks or damage - Structural concerns - Code compliance issues - Deferred maintenance
Inspection Outcomes:
Results may include: - Coverage approved as requested - Coverage approved with conditions - Required repairs before coverage - Modified terms or pricing - Coverage denied
Strategies for Maintaining Coverage
Several approaches help homeowners maintain coverage for aging roofs.
Documentation:
Maintain thorough records: - Professional inspection reports - Maintenance receipts - Repair documentation - Photos showing condition
Maintenance:
Demonstrable care supports coverage: - Regular inspections - Prompt repairs - Preventive maintenance - Clean gutters and drainage
Upgrades:
Strategic improvements help: - Replace damaged sections - Improve ventilation - Address flashing issues - Consider impact-resistant materials
When to Replace Your Roof
Timing roof replacement strategically can optimize insurance benefits.
Insurance-Related Timing Factors:
Coverage Benefits:: - New roof restores RCV coverage - Premium reductions possible - Better coverage terms - Improved claim potential
Cost Considerations:: - Current roof claim settlement potential - Expected future claim likelihood - Premium difference with new roof - Out-of-pocket replacement cost
Condition Indicators:
Consider replacement when: - Roof approaching coverage limitations - Multiple problem areas emerging - Repeated repairs needed - Insurance offering limited coverage
Claims with ACV Coverage
If you have ACV coverage and need to file a claim, understanding the process helps maximize recovery.
Maximizing ACV Settlement:
Document Condition:: Show your roof was well-maintained: - Maintenance records - Inspection reports - Photos of pre-loss condition
Challenge Depreciation:: If depreciation seems excessive: - Get professional condition assessment - Document remaining useful life - Request depreciation calculation review - Appeal if warranted
Consider Full Replacement:
Even with ACV settlement: - Adding funds for full replacement may make sense - New roof restores coverage - Long-term protection improves - Premium savings may offset cost
Alternative Coverage Options
When standard coverage is unavailable or inadequate, alternatives may exist.
Citizens Insurance (State Insurers):: - May offer coverage when private market won't - Different terms and conditions - Often higher rates - Assessment risks in some states
Surplus Lines Carriers:: - Accept risks standard market won't - Generally higher premiums - Less regulated protection - May have different claim procedures
Coverage Modifications:: - Higher deductibles for lower rates - Limited coverage for specific perils - Named peril vs. all-risk policies - Roof exclusion with separate coverage
Planning for Roof Replacement
Strategic planning optimizes both insurance and replacement timing.
Pre-Replacement Planning:
- Review current coverage status
- Understand claim potential
- Get replacement estimates
- Compare insurance scenarios
- Time replacement strategically
Financing Options:
Consider how to fund replacement: - Insurance settlement if claim exists - Home equity financing - Replacement savings fund - Contractor financing options
New Roof Insurance Benefits:
After replacement, expect: - Full RCV coverage availability - Premium reductions - Better coverage terms - Peace of mind
Conclusion
Insurance coverage for aging roofs requires understanding how age affects coverage type, depreciation impact, and available options. By maintaining your roof well, documenting its condition, and planning strategically, you can optimize coverage throughout your roof's life and make informed decisions about replacement timing.
Don't wait until coverage problems arise to address aging roof concerns. Regular professional inspections and proactive maintenance help maintain both your roof and your insurance protection.
Find qualified contractors who can assess your roof's condition and help you plan for its future.